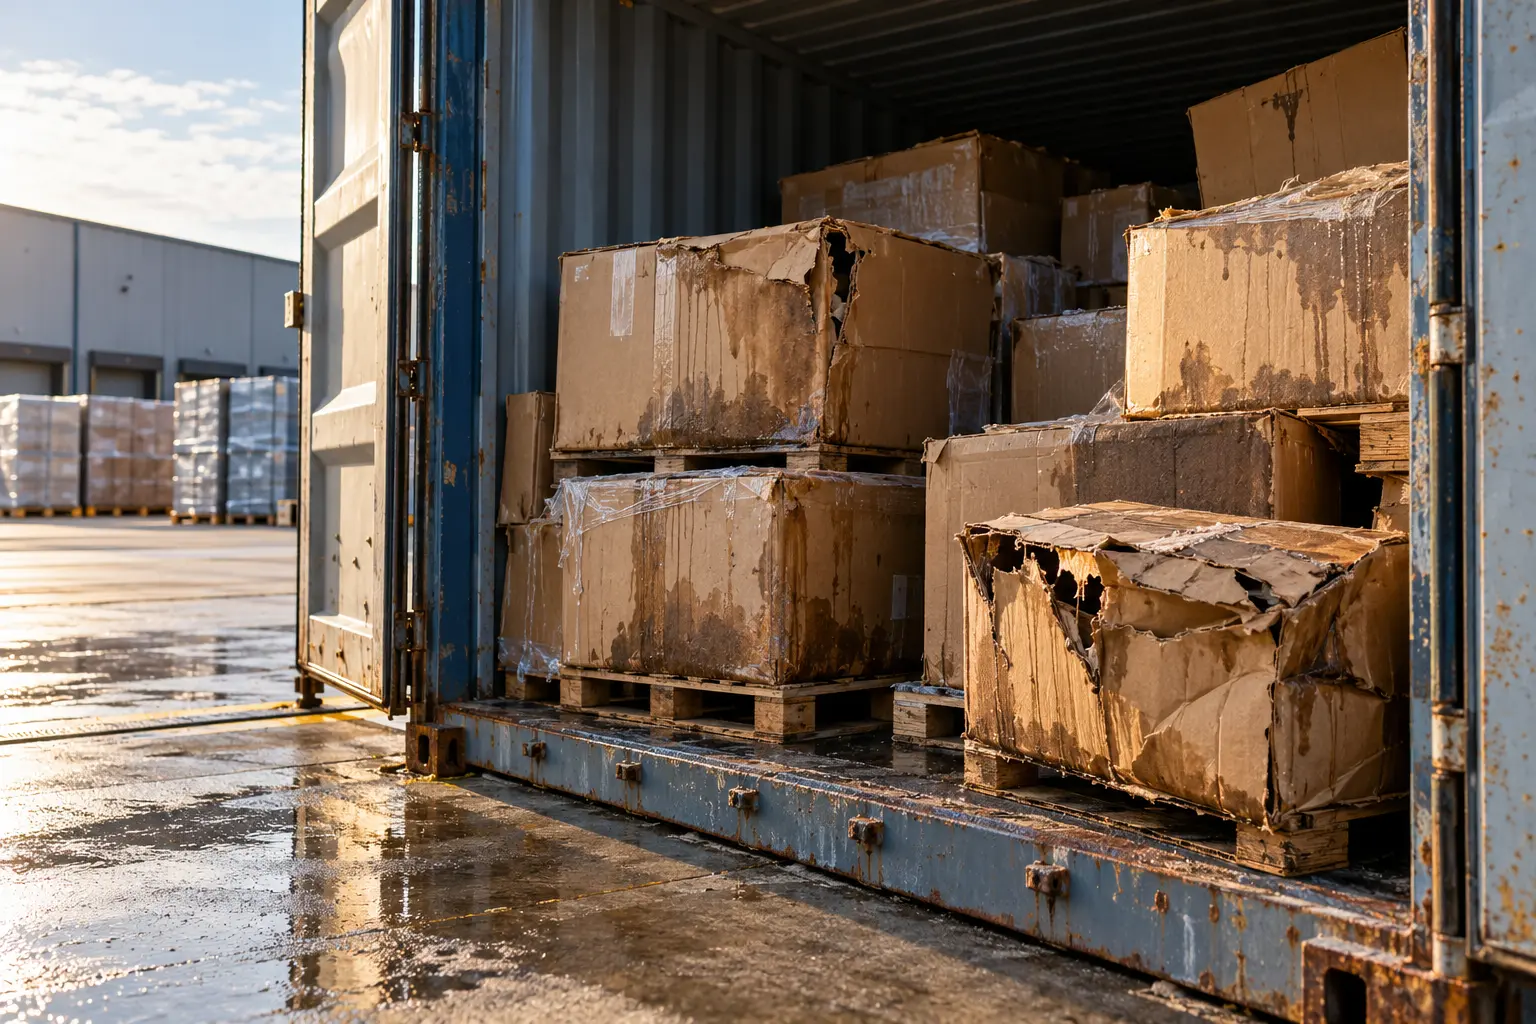
Cargo insurance and carrier liability are different
A business may have insurance protecting its goods in transit. A transportation company may also carry insurance covering its liability. These are different contracts with different insured parties, conditions and limits. The existence of the carrier’s insurance does not establish its responsibility for the full value of your goods.
| Question | Your cargo insurance | Carrier liability claim |
|---|---|---|
| What is reviewed? | Your insured interest, the loss and policy terms. | The transportation company’s responsibility under the contract and applicable law. |
| What can limit recovery? | Deductibles, exclusions, valuation provisions and coverage limits. | Liability defenses, contractual or statutory limits and claim requirements. |
| Who needs notice? | The insurer or designated claim recipient. | The relevant carrier or other responsible transportation party. |
Both paths can matter. Preserve the relevant rights and documents, and avoid signing a release without understanding its effect. Recovery through one avenue may affect the other.
Where public adjusting fits
A public adjuster represents the insured’s interests in the insurance claim. Active Claim Adjusters LLC reviews the policy and loss, documents damage and valuation, prepares the claim presentation and communicates with the insurer within the agreed scope.
A marine surveyor or technical specialist may inspect the goods and investigate cause. An attorney may be needed for a legal dispute, contract interpretation outside the adjusting engagement or litigation. The right combination depends on the shipment and the issues involved.
Start with the policy, not the label
Cargo-related coverage may appear in a marine cargo, inland marine, transit or stock-throughput policy. Some programs address goods during specified storage as well as transport. The actual wording, endorsements, insured parties and relevant locations determine what applies.
“Allied lines” is a broader property-insurance term, not a precise name for cargo coverage. Using the correct policy documents is more useful than relying on a general insurance category.
A denial or offer deserves a factual review
If an insurer has denied the claim or made an offer, keep its written explanation and the supporting calculation. A review can compare those reasons with the policy, photographs, surveys and valuation evidence. Missing records or unresolved factual questions may need further work. Deadlines, releases and prior settlements can affect the available options.
For the first conversation, have the policy or certificate if available, transport documents, the approximate loss amount and a short timeline. Scope and fees are agreed in writing before representation begins.
Start your cargo claim review →
Further reading
- Chubb: freight liability versus cargo insurance
- NAIC: insurance terminology, including allied lines
- NAPIA: the role of public insurance adjusters
This overview does not determine coverage or legal liability. Every claim needs its own policy, evidence and jurisdiction review.